Fewer Jobs, Lower Unemployment: A Clearer Housing Plan for Seattle and the Eastside
Friday Market Insight | October 16, 2026
By Jacob Blackford | Seattle + Eastside | Works Real Estate
Washington’s mixed September jobs report makes income confidence and cash reserves worth a closer look. It does not tell us what an individual home should sell for.
Washington reported fewer payroll jobs in September and a lower unemployment rate. For someone considering a home purchase or sale in Seattle, Bellevue or another Eastside community, that combination can sound contradictory. It is also a good reason to slow down the interpretation before changing the plan.
The practical takeaway is to test how a move fits your income, available cash and timeline. Buyers should know what remains after closing and how the budget would hold up under a realistic interruption. Sellers should understand the cost of their own timing choices and the evidence from comparable homes. Neither decision becomes automatic because a statewide number moved.
This week's most useful development is the October 14 Washington Employment Security Department report. Unlike a national mortgage headline, it gives us a fresh view of the state's employment backdrop. Unlike a property-level market analysis, it cannot establish the demand for a particular Seattle house or Eastside condominium. Keeping those jobs separate makes the report more useful.
What the report actually says
ESD estimated that Washington lost 15,400 nonfarm payroll jobs in September, seasonally adjusted. The unemployment rate fell from 4.9% in August to 4.8%. September estimates are preliminary.
The payroll decline included 10,400 government jobs and 5,000 private-sector jobs. Some private industries expanded: professional and business services added 1,800 jobs, construction added 1,500, and information added 1,400. ESD said none of the information-sector increase came from software publishing. Statewide payroll employment remained 9,200 jobs, or 0.3%, above September 2025.
That is a mixed report, not evidence of uniform improvement or contraction. It also is not a count of 15,400 newly unemployed homebuyers. Jobs and people are different measures, and a net payroll change is not a layoff tally.
| Washington payroll change | September 2026 versus August | Scope |
|---|---|---|
| Government | -10,400 jobs | Statewide, seasonally adjusted |
| Private sector | -5,000 jobs | Statewide, seasonally adjusted |
| Total nonfarm | -15,400 jobs | Statewide, preliminary |
Source: Washington ESD, October 14, 2026. The two sector changes sum to the total. These are employment estimates, not King County housing statistics.
Why fewer jobs and lower unemployment can coexist
The unemployment rate is the number of unemployed people as a share of the labor force. The labor force includes people working and people who meet the criteria for being unemployed. Someone without a job who is not actively looking generally is not counted as unemployed, with specific exceptions such as temporary layoffs.
Payroll estimates answer a different question about jobs at employers. The measures have different coverage and methods. They should not be treated as two interchangeable scoreboards. ESD attributed the falling rate partly to fewer unemployed people and partly to a smaller labor force.
For a housing decision, ask what the number actually measures before asking whether it is good news. A lower unemployment rate does not guarantee stronger household income. A weak payroll month does not prove that every employer is reducing staff, or that every household will postpone moving.
The same discipline applies to location. This release is statewide. Its Seattle/Bellevue/Everett references cover a wider area than King County. September county estimates are due October 20, after this edition. We should not relabel the state result as a Seattle or Bellevue job-loss count.
What this means locally
Employment can influence housing through several channels. An income change affects the payment a household can support. Uncertainty can change a household's willingness to commit even when its current paycheck is unchanged. A new role, relocation or return-to-office requirement can also change the reason for moving. These are mechanisms to consider, not measured effects established by this one release.
The first useful distinction is between your household and the market around it. A household with dependable income, sufficient reserves and a long ownership horizon may make a sound purchase during a cautious market. A household with uncertain near-term income may benefit from a smaller commitment or a longer preparation period, even if attractive homes are available. The same headline can support different choices because the underlying circumstances differ.
The second distinction is between nearby properties. A Seattle condominium has building-level costs and documents to investigate. A detached Eastside home may require a different maintenance allowance. A townhome's shared obligations depend on its actual ownership and governing documents. The jobs report cannot replace those checks or tell you that a more expensive alternative is affordable.
Last week's Seattle and Eastside inventory feature explains why supply should be compared by geography and property category. This week adds a different question: even if the property looks competitive, does the household plan have enough room?
Buyers: separate the payment from the cash cushion
Start with a complete monthly ownership budget. Principal and interest are only part of it. Include property taxes, insurance, applicable mortgage insurance and association dues, then plan separately for utilities, maintenance and other household commitments. Use actual property information and lender estimates as they become available.
Then calculate the cash left after the transaction. Account for the down payment, closing costs, moving costs and immediate work. Money earmarked for a known project should not quietly become the emergency fund in a second calculation. The same dollar cannot protect two commitments at once.
Consider a hypothetical household with $60,000 available after its down payment and closing costs. It sets aside $12,000 for moving and identified immediate work, leaving $48,000. If its essential monthly spending after the move would total $8,000, that remaining cash equals six months of those expenses. If spending would instead total $10,000, the same cash covers 4.8 months.
This is simple division, not a recommendation that every household needs the same reserve. The example assumes no replacement income and no investment return. It excludes new emergencies beyond the planned budget. A lender's required reserves and your personal comfort level can also differ. Its purpose is to make the assumptions visible.
Now ask which income supports that spending. If overtime, a bonus or equity compensation disappeared for a period, what would change? Discuss any employment or compensation change with your lender promptly, especially during a purchase. A personal budgeting exercise does not establish loan eligibility or replace an updated underwriting review.
The useful decision may be to buy at the original budget, reduce the price range, postpone discretionary renovations or wait while rebuilding cash. Choose the adjustment that addresses the actual constraint. A discount does not solve an income problem if the resulting payment still depends on money you cannot count on.
Sellers: plan your exposure before choosing your pace
For sellers, the report is a prompt to examine timing and execution, not an instruction to cut a price by a particular percentage. Begin with the homes a buyer can actually choose instead of yours, recent relevant sales and current showing feedback. Use close comparisons in location, property type, condition and price range.
Next, look at your own timeline. Are you paying for an empty property while living elsewhere? Does your next move require sale proceeds? Is the property occupied, and how much flexibility do you have to prepare and show it? A seller with low carrying costs and flexibility has a different decision from one with a firm relocation deadline.
Build a calendar that includes preparation, marketing, the contract period and the move. Put a cost beside an extra month and identify what cash is available if the schedule extends. This is scenario planning. It does not mean predicting that a listing will take a particular number of days to sell.
Then reduce avoidable uncertainty for a buyer. Have accurate information about recurring costs, completed work and the property's condition ready. Make access workable. Answer material questions through the appropriate documents and professionals. Clear information helps a buyer evaluate the commitment; it does not guarantee an offer or remove the need for negotiation.
A measured response is more useful than reacting to an employment headline with a blanket concession. If the property is not attracting the expected interest, determine whether the problem is price, condition, presentation, access or a very narrow buyer pool. The response should follow the evidence from the listing and its alternatives.
A softer jobs report does not promise cheaper financing
There is another reason to avoid turning this release into a simple buying signal. Employment is only one part of the economic picture. The Bureau of Labor Statistics reported on October 14 that national consumer prices rose 0.6% in September on a seasonally adjusted basis and 3.7% over the prior year before seasonal adjustment. Those are national consumer-price measures, not Seattle home-price changes.
Mortgage pricing reflects more than the latest jobs report or a Federal Reserve decision. A weaker employment reading does not guarantee a lower mortgage quote next week. Nor does a possible future refinance make an unaffordable payment workable today. The current loan and ownership budget need to stand on their own.
For a purchase in progress, use a fresh written financing comparison and confirm the terms with the lender. Monday's Q&A on comparing mortgage offers develops that separate decision. This feature deliberately does not turn a national rate average into a quote for a Seattle or Eastside borrower.
The signals to watch next
The October 20 county release should provide a closer geographic view, although a county estimate will still not describe every neighborhood or employer. Revisions to September's payroll estimates also matter. A preliminary monthly change can look different as more information becomes available.
For housing, watch whether close substitutes are going pending, how sellers respond to sustained feedback and whether the financing available to your household changes. Those observations are more actionable than waiting for all economic headlines to agree. They also help distinguish a temporary pause from a change that deserves a new strategy.
My reading is cautious but practical: preserve flexibility, make the cash plan explicit and evaluate the actual property. The state report gives us a reason to ask better questions. Your household finances and local alternatives provide the basis for the answer.
If you are planning a Seattle or Eastside move, start a conversation about your city, property type and timing. We can connect the market evidence to the decisions your move requires.
Sources and reporting notes
- Washington ESD, September employment release, October 14, 2026. Preliminary September statewide data; county release scheduled October 20.
- BLS, How the Government Measures Unemployment, methodology reviewed October 15, 2026.
- BLS, September Consumer Price Index, October 14, 2026. National CPI-U; monthly changes seasonally adjusted, annual changes not seasonally adjusted.
- CFPB, Figure out how much you want to spend, modified February 18, 2026; reviewed October 15. Budget guidance, not individual lending advice.
Final source check: October 16, 2026, 6:42:53 AM Pacific (PDT). Reporting window: October 9, 2026, 6:42:53 AM through October 16, 2026, 6:42:53 AM PDT. Primary employment, inflation, methodology, budget guidance and photograph rights were rechecked before release. Calculations and decision scenarios are original analysis, with hypothetical household inputs. No client case or forecast of local prices is represented.
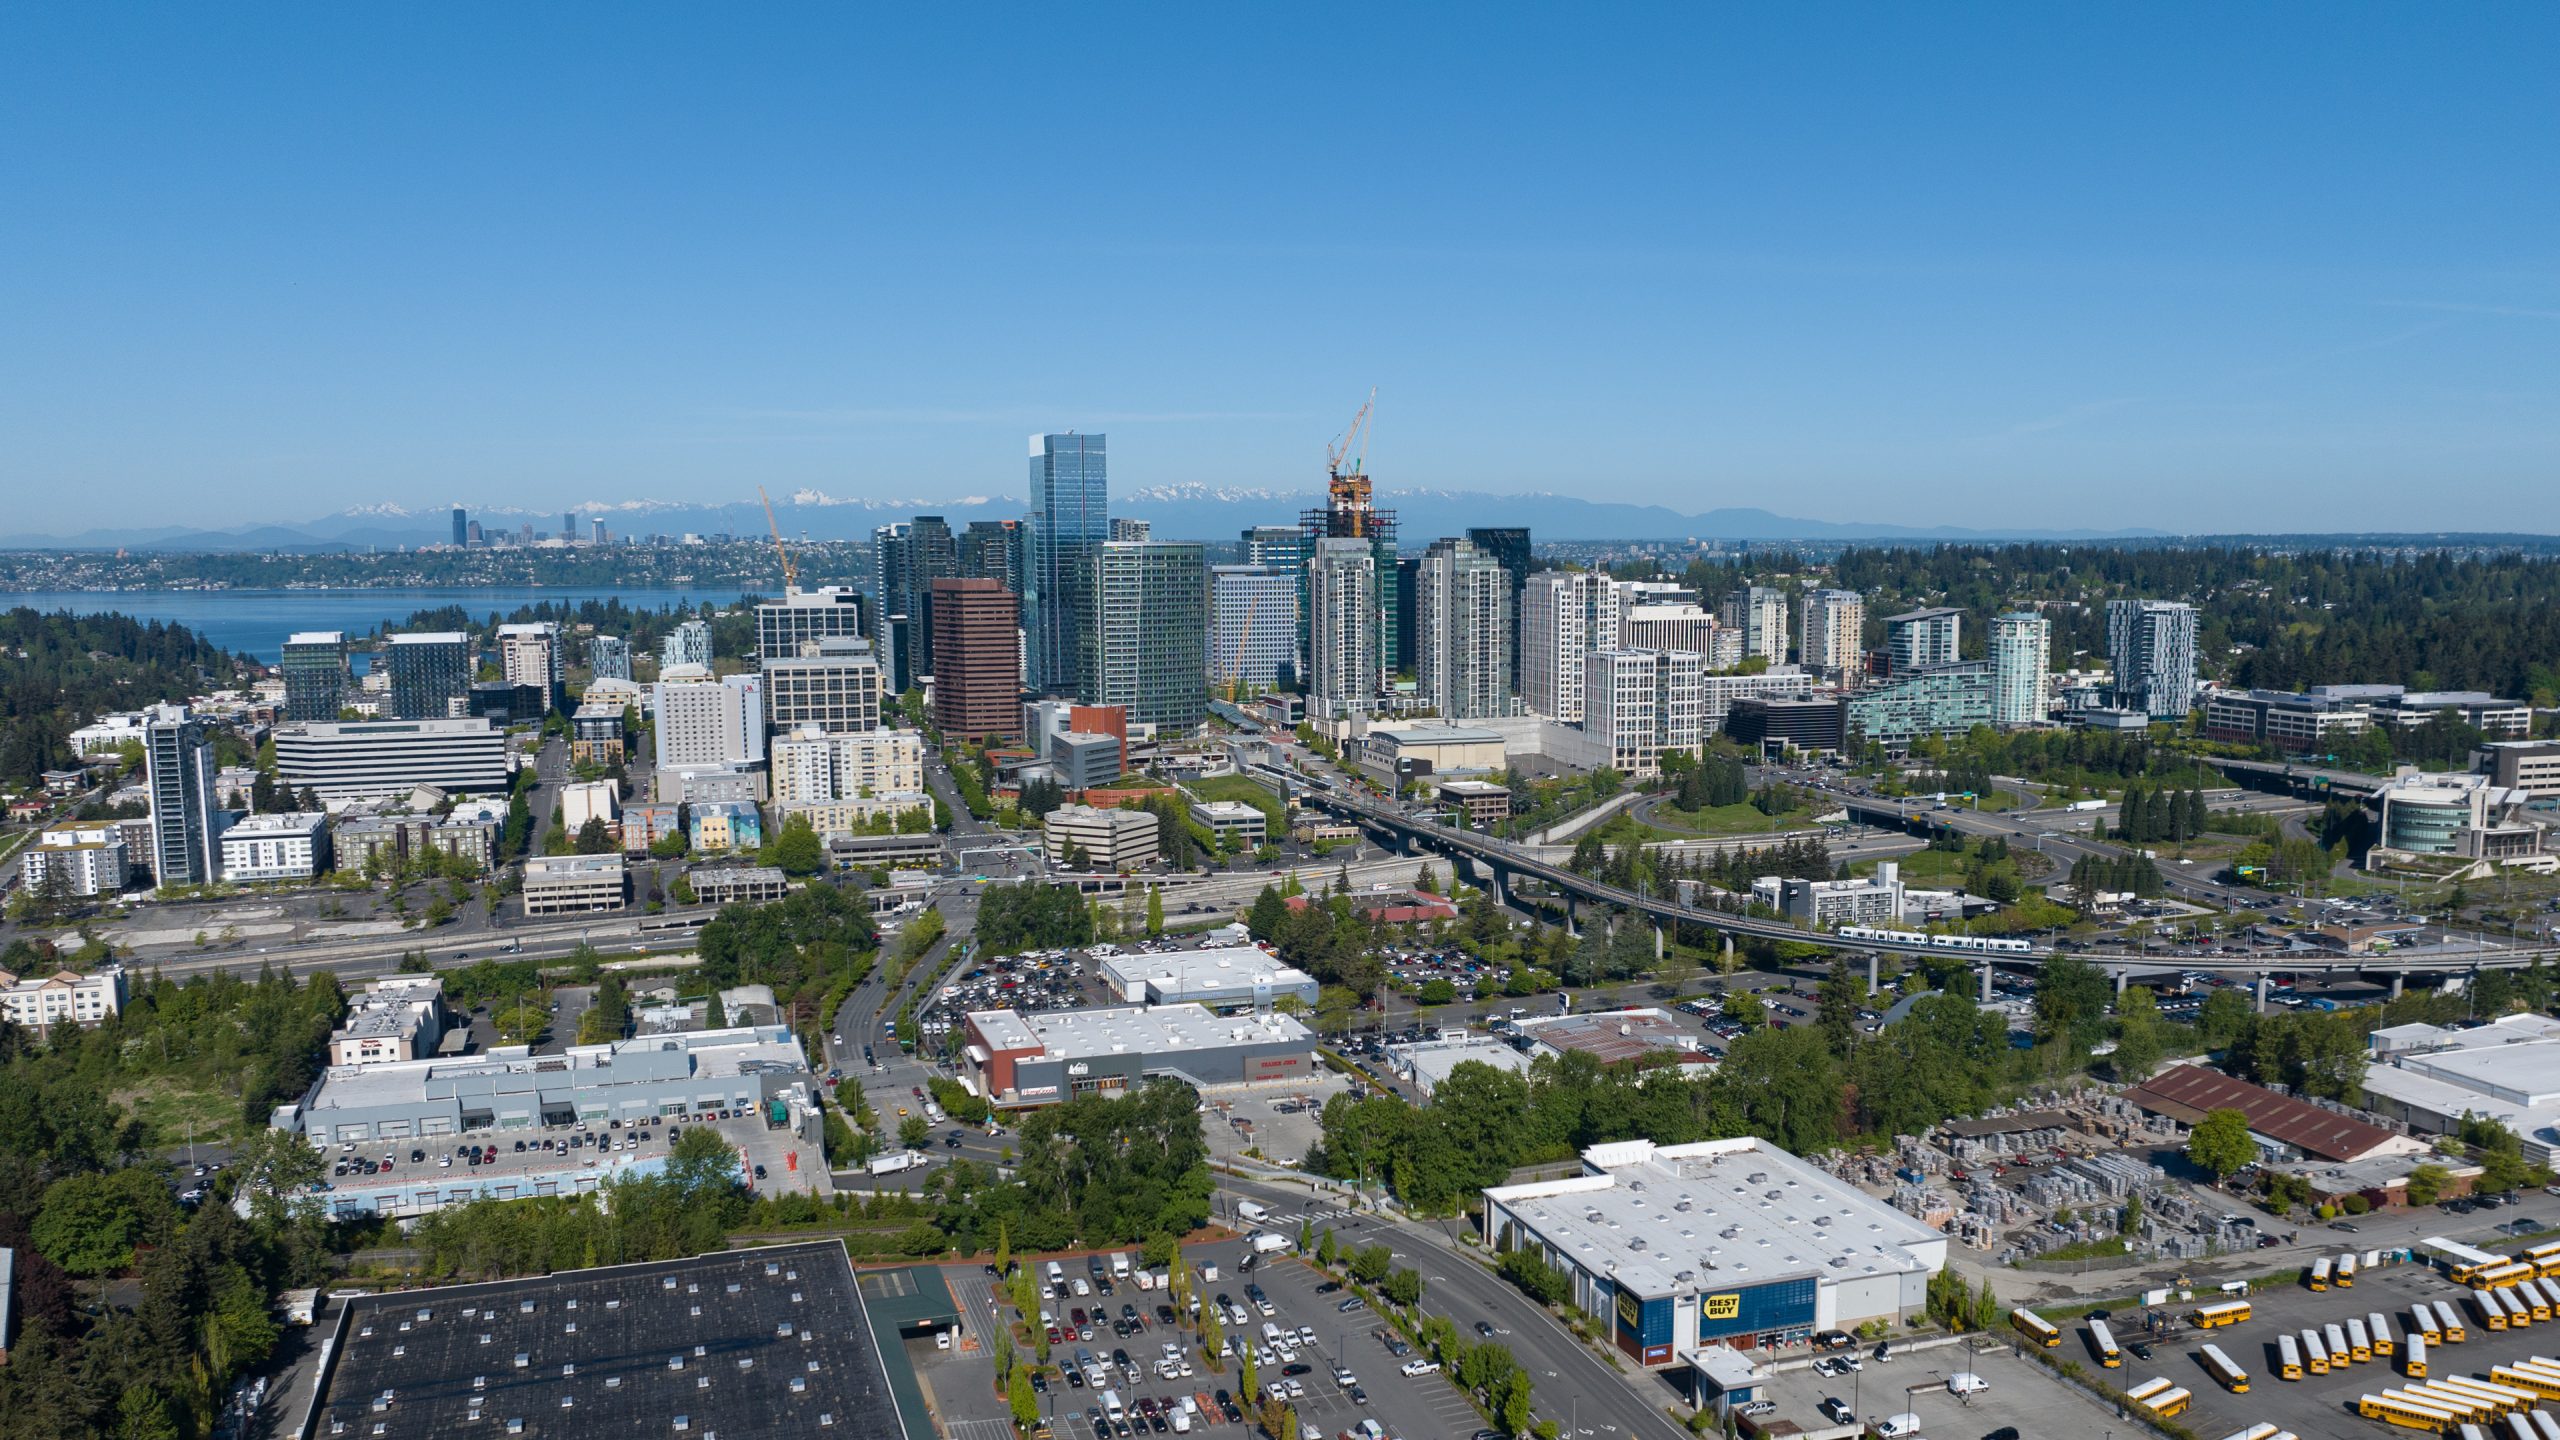
Photo: Downtown Bellevue, May 10, 2024, Spicypepper999, Wikimedia Commons, CC0 1.0. Archival context photograph, not current inventory.
